Zhou Jing
On the morning of January 4th, at the invitation of the School of Mathematics, Physics and Statistics, Professor Sun Jie, a Distinguished Professor of Curtin University, Australia, and a Chair Professor of the National University of Singapore, gave an academic report titled "Risk-averse Optimal Control Models under Uncertainty and an Improved Progressive Hedging Algorithm" in Room 1308 of the Administration Building. Heads of the School and representatives of faculty and students attended the lecture.
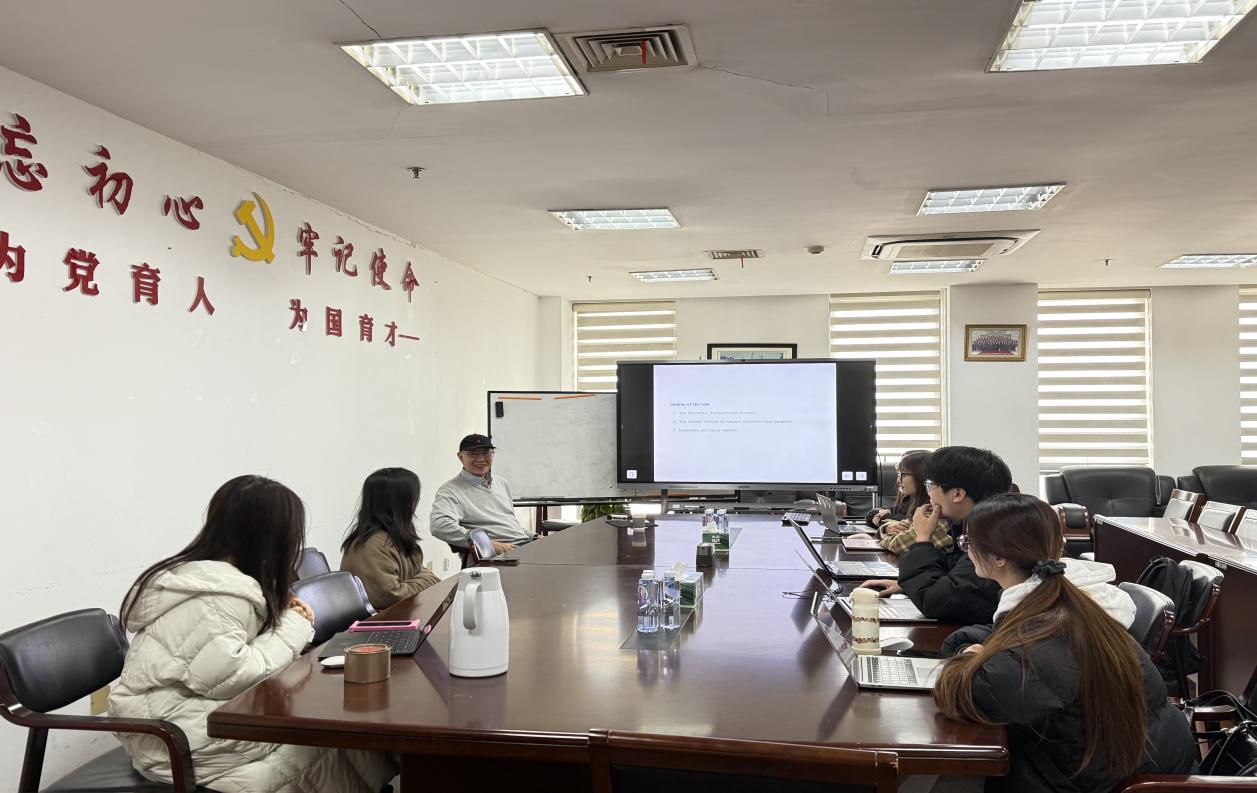
In his report, Professor Sun started from the classic newsvendor model, systematically introduced the basic principles of stochastic optimization, and then extended the discussion to the field of financial optimization management, elaborating on optimization decision-making methods for stochastic processes. He pointed out that stochastic optimization, which deals with mathematical optimization problems containing random data, is characterized by the introduction of random variables as coefficients — a feature that makes it closer to reality than deterministic mathematical optimization and gives it broader practical value.